Upgrade - Boost Money
Upgrade, Inc.
- 4.0
- 50.00 Reviews
- 50.00K
- Downloads
- Free
- Price
Screenshots
Upgrade - Boost Money Pros and Cons
Pros
- Simple interface makes balance tracking easy for beginners.
- Useful spending insights can help identify costly habits.
- Supports goal setting for saving toward specific purchases.
- Quick account overview reduces the need to check multiple apps.
- Helpful reminders can encourage more consistent money management.
Cons
- Some features may require a paid subscription or in-app purchase.
- Financial data requires trust in the app’s privacy and security practices.
- Bank connections may occasionally fail or need to be renewed.
- Notifications can become distracting if too frequent.
- Limited customization may not suit users with complex budgets.
 Analysis by All-app
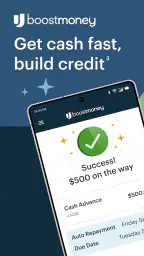
I approached Upgrade - Boost Money as a practical finance app rather than something to open once and forget. Its basic promise is easy to understand: bring spending, saving, and credit-building into one place. In my experience, that combination is most useful when it becomes part of a repeatable money routine, not when it is treated as a magic fix for every financial problem.
The app comes from Upgrade, Inc. and is free to download. It is aimed at an Everyone audience, so the presentation feels approachable enough for someone who is just beginning to organize personal finances. At the same time, anyone using it for credit-related decisions should slow down and read each screen carefully. A friendly interface does not remove the need to understand what you are agreeing to or how a financial product fits your own situation.
How I built a reliable everyday workflow
My preferred starting point was deliberately simple. I treated the app as a central checkpoint: first review what I planned to spend, then look at the saving side, and only after that think about the credit-building angle. This order matters because it keeps credit from becoming the only goal. A stronger credit profile is useful, but it should support a sustainable budget rather than encourage extra spending.
For a normal weekday, I would open the app before making a larger purchase and use it to reconnect the decision with my broader money plan. Later, I would return for a quick review instead of repeatedly checking every small transaction. That habit made the experience less stressful. The useful question was not “Can I buy this?” but “Does this purchase still make sense after my saving priorities and upcoming obligations?”
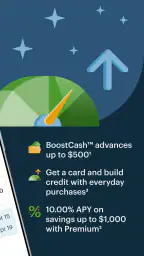
This is where the app’s three-part design can be helpful. Spending gives the day-to-day activity a place, saving gives future needs more attention, and credit-building adds a longer-term objective. I found that separating those mental jobs reduced the temptation to judge every financial decision by a single number. Someone who only wants a basic expense tracker may find the broader setup unnecessary, but users who want one finance-focused home screen may appreciate the structure.
A realistic example would be a person preparing for a recurring household bill while also trying to avoid impulsive purchases. Instead of waiting until the end of the month to discover that the bill has become difficult, they can make the saving goal part of the routine and check spending against it. The important insight is that the app works best as a prompt for earlier decisions. It cannot create room in a budget that does not exist, but it can make the trade-off easier to notice.
I also recommend choosing one consistent review moment. For me, a short check after a regular income deposit would be more useful than opening the app randomly throughout the day. During that check, I would confirm what money is available for ordinary spending, review whether the saving plan still matches the next obligation, and then look at credit-related activity with a more cautious eye. This three-step order prevents the credit feature from distracting me from immediate cash flow.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What to check before relying on it
Before making the app part of a serious routine, I would read every explanation attached to a financial action. Terms connected with spending, saving, or credit can have consequences that are easy to overlook when the screen is designed to feel quick. I would pay particular attention to eligibility language, repayment expectations, account requirements, and any wording that changes depending on the action selected.
I would also decide what role the app is supposed to play. If it is the main place for a user to manage money, then consistency is essential. If it is only a companion to an existing bank account, the user should avoid treating the app’s view as a complete picture until they have checked that all relevant activity is represented. That is not a criticism of this particular product; it is a sensible safeguard whenever more than one financial service is involved.
The app is currently at version 1.3.0, and I would keep it updated through the normal device process. Updates can affect navigation and the way information is presented, so a quick look around after an update is worthwhile. I would not assume that a familiar button still leads to the same place without checking. This small habit is especially useful in a finance app, where an unnoticed change in a setting can create confusion later.
Another setting-related habit is to make notifications serve a purpose rather than allowing every alert to become background noise. I would keep reminders that help me act, such as prompts connected with reviewing money or checking an important change, while being more selective about anything that encourages constant monitoring. The best notification is one that leads to a clear action. Too many vague alerts can make a finance routine feel urgent even when nothing needs immediate attention.
Privacy deserves the same practical attention. I would review the device’s notification display and avoid showing sensitive financial details on a lock screen shared with other people. I would also use the phone’s available security controls and avoid opening financial information on an unfamiliar device. These are ordinary precautions, but they matter more than decorative customization when an app is handling personal money information.
One of the more useful ways to test the setup is to perform a small, low-pressure review before using it for a major financial decision. Check whether the balance, activity, and saving intentions are easy to interpret. If the first session leaves you unsure which figure matters, that is a sign to pause and learn the layout rather than rushing into a larger action. Confidence should come from understanding the screen, not from assuming that a polished design explains everything.
Shortcuts that make the routine easier
Experienced users usually do not try to use every part of a finance app every day. I would create a small repeatable sequence and keep it stable: open the app, review spending, confirm the next saving priority, and then inspect credit-related information only if there is a reason. This is faster than wandering through every available section, and it keeps the app connected to decisions that matter.
A second useful shortcut is to prepare for predictable expenses before they become urgent. If a bill, trip, or annual payment is already known, I would make it part of the saving conversation early rather than waiting for the payment date. The app’s value here is behavioral: it gives the user a place to revisit the intention. The actual success still depends on whether the user contributes enough and avoids spending that money elsewhere.
I would also separate “review” from “action.” First look at what happened; then decide what to change. Combining both too quickly can lead to emotional decisions, especially after an unexpectedly expensive day. A calm review might show that the purchase was unusual and harmless, or it might reveal a pattern that deserves attention. Giving myself a pause makes the app more useful as a planning tool and less like a source of instant reactions.
For credit-building, the shortcut is restraint. I would not use a credit-oriented feature simply because it is available, and I would not increase spending to chase an abstract improvement. The better workflow is to understand the terms, use only what fits the budget, and treat timely, manageable behavior as more important than speed. Anyone already carrying expensive debt should compare the app’s role with a broader repayment plan instead of assuming that credit-building is the first priority.
There is also a helpful division between personal review and shared household discussion. If two people manage money together, one person can use the app for the daily check while both agree on the saving priorities and larger spending decisions. That avoids the common problem of one person seeing information without the other understanding the plan. The app can support coordination, but it cannot replace an honest conversation about who is responsible for each obligation.
Users should remember that “free” refers to the app’s price, not to every possible financial outcome associated with using a finance product. I would never make a decision based only on the fact that downloading it costs nothing. Instead, I would inspect the details of any account, card, or credit-related option before proceeding. This is one of the most important distinctions for newcomers, because a free download can still lead to products with their own terms.
Where the app’s limits become important
The biggest limitation is conceptual: combining several money tasks in one app can feel convenient, but it can also blur the difference between tracking, saving, and borrowing. I had to keep reminding myself that these are separate decisions. A user who wants a highly detailed budgeting system, extensive investment research, or specialist debt planning may be better served by dedicated tools alongside this one.
I would also avoid treating the credit-building side as a guaranteed shortcut. Credit outcomes depend on the user’s complete financial behavior and on the terms of the product involved. The app may make the process easier to approach, but it cannot make responsible borrowing unnecessary. If someone is looking for immediate access to money without a clear repayment plan, this is not the app I would recommend as a first step.
There is a similar limit with saving. A digital goal can make an intention visible, yet visibility is not the same as progress. If income changes from week to week, the user may need to adjust contributions rather than blindly following an old target. I would rather set a modest, realistic routine and review it regularly than choose an ambitious target that repeatedly fails. The app is most helpful when it reflects reality instead of pretending circumstances are fixed.
Compared with a traditional bank app, this product appears more focused on connecting everyday spending with saving and credit-building behavior. A bank app may remain the better primary tool for someone who wants a complete view of established accounts, transfers, and institution-specific services. Compared with a standalone budgeting app, Upgrade - Boost Money may feel less appealing to users who want detailed categories, elaborate reports, or deep customization. Its strength is the combined direction, not necessarily specialist depth in every area.
That trade-off makes the audience fairly clear. I would recommend it to someone who wants a straightforward starting point for coordinating spending, saving, and credit habits, especially if opening several unrelated apps feels discouraging. I would be more cautious about recommending it to a person who already has a carefully tuned financial system and only needs advanced analysis. In that situation, adding another central dashboard could create duplication rather than clarity.
Another practical question is whether the app suits someone who dislikes financial routines. My honest answer is only if they are willing to create a small habit around it. No finance app can compensate for never reviewing balances, ignoring notices, or accepting terms without reading them. The simpler the routine, the more likely it is to last: one scheduled check, one clear saving priority, and no unnecessary daily obsession.
The app has an average rating of 4.0 from around 160 ratings, with over 50,000 installs, which suggests a modest but real user base rather than a product I would treat as universally established. I see that as a reason to evaluate it personally and carefully, not as a reason to dismiss it. The free price lowers the barrier to trying the interface, while the financial decisions inside it still deserve the same caution I would apply elsewhere.
My verdict after using it as a repeatable money tool
Upgrade - Boost Money works best when I use it as a disciplined checkpoint rather than an all-purpose financial answer. Its appeal comes from putting spending, saving, and credit-building in the same conversation. That can make a vague intention more concrete, particularly for someone who wants to develop better habits without starting with a complicated budgeting system.
My strongest recommendation is to begin with one workflow and resist the urge to optimize everything immediately. Review spending first, connect saving to a real upcoming need, and approach credit features only after understanding their terms. Then keep the routine consistent for long enough to see whether the app genuinely improves decisions. This approach is more valuable than chasing every setting or checking the screen repeatedly.
I would skip it if I needed specialist budgeting reports, a complete replacement for an established bank relationship, or a rapid solution to serious debt. I would also skip any credit-related action that did not fit comfortably within my repayment ability. In those situations, a dedicated budgeting tool, a direct conversation with a financial professional, or a simpler spending plan may be more appropriate than adding another financial product.
For the right user, though, the app offers a sensible bridge between daily money choices and longer-term credit awareness. It is free, available for devices running iOS 12 or later, and presented for Everyone, making the first step relatively approachable. My final view is positive but measured: use it to build a calm, repeatable process, read the details before acting, and let your real budget—not the app’s convenience—set the limits.
Frequently Asked Questions
What is Upgrade - Boost Money, and how does it work?
Upgrade - Boost Money is a personal finance app designed to help users manage spending, monitor credit-related information, and explore financial products offered through Upgrade. After creating an account, you may be able to view personalized offers, track transactions, review account details, and access tools intended to support better money management. Available features and offers can vary depending on your eligibility, location, and the information provided during registration.
Is Upgrade - Boost Money a legitimate and safe app to use?
Upgrade - Boost Money is associated with Upgrade, a financial technology company that provides banking, credit, and personal finance services. The app may use security measures such as account authentication, encryption, and device verification to help protect user information. However, no online service is completely risk-free. Download it only from an official app store, use a strong password, enable available security options, and carefully review permissions, privacy policies, and account terms.
Can I borrow money or apply for a credit product through the app?
The app may allow eligible users to explore or apply for certain Upgrade financial products, including personal loans, credit cards, or banking-related services. Approval is not guaranteed, and eligibility may depend on factors such as credit history, income, identity verification, and applicable lending criteria. Before accepting any offer, review the annual percentage rate, fees, repayment schedule, minimum payments, and total cost so you understand the commitment.
Does using Upgrade - Boost Money affect my credit score?
Credit impact depends on the specific feature or product you use. Checking whether you are prequalified for some offers may involve a soft credit inquiry, which generally does not affect your credit score. Submitting a formal application or opening a credit account may result in a hard inquiry and could affect your credit profile. Always read the disclosure shown in the app before proceeding, because policies may differ by product and applicant.
Are there fees, eligibility requirements, or limitations I should know about?
Requirements and costs depend on the Upgrade service you choose and your personal circumstances. You may need to meet age, residency, identity, income, and credit criteria, while some products can include interest charges, annual fees, late fees, origination fees, or other costs. The app itself may be free to download, but that does not mean every financial product is free. Check the current pricing, terms, availability, and privacy information before signing up or submitting an application.